Pre-approval you can trust
Income, assets and credit reviewed before the letter goes out — not after the offer is accepted. Letters are written to match the offer price.
For real estate agents
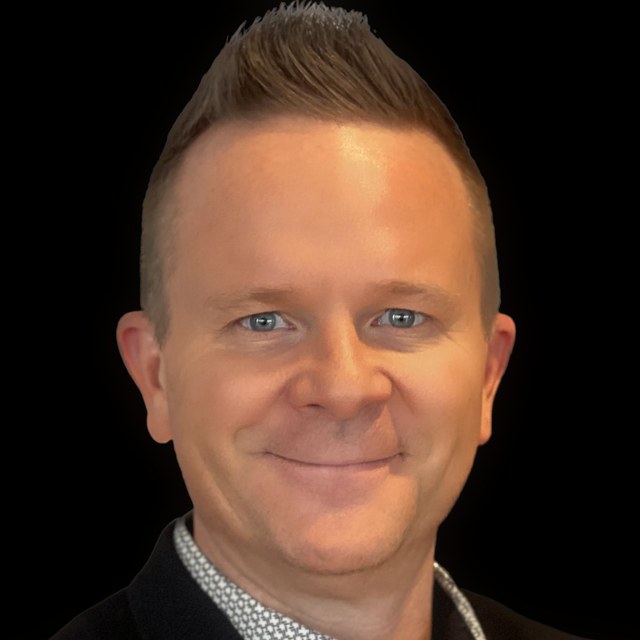
You find the house. Scott makes the financing land — fast enough and communicative enough that you never have to chase a status update or explain a lender's silence to your client.
7
Days a week Scott answers — showings and offer deadlines included
10 min
For updated payment + cash-to-close on offer day
1 call
To the listing agent with every offer submitted
1–2 days
Typical pre-approval turnaround once documents are in*
* Timing varies by file and depends on receiving complete documentation. Turnaround figures are typical, not guaranteed. This is not an offer to enter into an agreement; not all customers will qualify. Rates, programs and terms are subject to change. All loans subject to credit and property approval.
What working with Scott looks like
Agents lose houses to slow lenders, quiet lenders, and lenders who write a pre-approval letter before they've read a pay stub. Scott built his process to be the opposite of all three.
Income, assets and credit reviewed before the letter goes out — not after the offer is accepted. Letters are written to match the offer price.
Text Scott the address and price. Updated payment and cash-to-close typically come back within ten minutes, even on a Sunday.
With every offer your buyer submits, Scott calls the listing agent personally, vouches for the financing, and leaves a cell number.
Appraisal ordered, appraisal in, conditions cleared, clear to close — you and your buyer hear it the moment it happens.
Realistic timelines set on offer day and a file structured the way underwriting reads it, so the date on the contract is the date you close.
The checklists and guides on this site mean your buyers arrive knowing what pre-approval is, what cash to close means, and what not to do under contract.
How agents use this site
The calculator answers the payment question before you drive anywhere. The checklists get documents in fast. The guides bust the 20%-down myth so you spend showings on houses, not homework. Nothing on this site collects a single piece of your client's information.
Scott Synovic and Fairway Independent Mortgage Corporation are not real estate brokerages. Buyers may work with any licensed real estate agent of their choosing, and no real estate professional is required to use any particular lender. Any co-marketing with real estate professionals is conducted in accordance with RESPA Section 8. Fairway pays only fair market value for services actually provided and does not compensate for referrals.
 Scott · Loan Officer
Agents
Text him the address and the buyer's name. He'll take it from there and keep you in the loop at every milestone.
Applications happen on Fairway's secure site — never here.
There’s a whole other side to this site
Scott also originates reverse mortgages for homeowners 62 and older — HECM, HECM for Purchase, the works. Flip the site over for the plain-English version: what it is, what it is not, and whether it fits.
Flip to Reverse