You keep the title
A reverse mortgage is a loan secured by your home, like any mortgage. The lender does not own your house. You do, the whole time.
The flip side · For homeowners 62+
A reverse mortgage is one of the most misunderstood tools in retirement — mostly because the people explaining it are either selling it or scared of it. Scott does both sides of the business, forward and reverse, so you get the honest version: what it is, what it is not, and whether it fits.
Scott · Fairway Reverse
forward and reverse
* No monthly principal and interest payment is required, but you must keep paying property taxes, homeowners insurance and any HOA dues, and maintain the home. Interest accrues and the balance grows over time.
What it actually is
A Home Equity Conversion Mortgage (HECM) is an FHA-insured loan for homeowners 62 and older that turns part of the equity in your home into money you can use now — without a required monthly mortgage payment and without giving up ownership. The loan is repaid when the last borrower sells, moves out for good, or passes away, usually from the sale of the home.
A reverse mortgage is a loan secured by your home, like any mortgage. The lender does not own your house. You do, the whole time.
You can make payments if you want to, but you do not have to. Interest and fees are added to the balance instead, so the balance grows over time and your equity shrinks.
Property taxes, homeowners insurance, HOA dues, upkeep. Falling behind on those is the one way a reverse mortgage becomes due early — so Scott talks about it on day one, not at closing.
HECMs are FHA-insured. If the home sells for less than the balance when the loan comes due, FHA insurance covers the difference. Neither you nor your heirs owe more than the home is worth when it is sold to repay the loan.
Four ways people use it
The most common use. The reverse mortgage pays off your current loan first, which eliminates the monthly principal-and-interest payment. Whatever is left is yours to take as a lump sum, a line of credit, monthly draws, or a mix.
Take little or nothing now and leave the rest as a HECM line of credit. The unused portion grows over time, independent of your home's value, and it cannot be frozen or cancelled as long as you meet the loan terms — which is why some financial planners treat it as a retirement safety valve.
Set up "tenure" payments that continue for as long as you live in the home, or "term" payments for a set number of years. Useful for covering a gap between what retirement income brings in and what the month costs.
HECM for Purchase (H4P) lets buyers 62+ purchase a home — closer to the grandkids, on one level, in a 55+ community — with a larger down payment and no required monthly mortgage payment afterward. One closing, one set of costs. Scott walks both sides of the deal.
Is it for you?
Scott does the forward side too, so there is no incentive to steer you here. These are the patterns that usually say yes — and the ones that usually say wait or no.
Scott · Loan OfficerOften a good fit
Worth a harder look first
Six myths, busted
The bank takes the house, the kids inherit the debt, you can be thrown out — all of it comes from a different decade, a different product, or a bad mailer. Tap each one.
The truth: No. You keep the title and you keep living there. The lender has a lien, exactly like a regular mortgage. The loan is repaid when the last borrower leaves the home for good — usually from the sale.
The truth: HECMs are non-recourse. Heirs can keep the home by paying off the balance or 95% of the appraised value, whichever is less, or they can sell it and keep whatever equity remains. They never owe more than the home is worth when it is sold to repay the loan.
The truth: As long as you live in the home as your primary residence and keep up with taxes, insurance, HOA dues and maintenance, the loan stays in place. Those obligations are the whole rulebook, and Scott goes through them before anyone signs anything.
The truth: Some of the most carefully planned retirements use a reverse mortgage line of credit as a buffer — so a bad market year does not force the sale of investments. It is a tool. Used well, it is a conservative one.
The truth: HECM for Purchase has existed since 2009. Buyers 62+ bring a larger down payment, the reverse mortgage covers the rest, and there is no required monthly mortgage payment afterward.
The truth: Actually, someone does — by law. Every HECM borrower completes a session with a HUD-approved counselor who does not work for the lender, before the application can move forward.
How it works
HUD-approved counseling sits between the conversation and the application, by law. Scott thinks that is the best rule in mortgage lending.
What you keep doing, for the life of the loan
Text or call Scott. Your goals, your home, your month. He will tell you honestly whether a reverse mortgage is worth a closer look — and if a forward refinance, a HELOC, or doing nothing is the better move, you will hear that instead.
A session with a HUD-approved counselor who does not work for Fairway. Required by law, usually about an hour, by phone or in person. You receive a certificate that lets the application proceed.
Income, credit history, and your record of paying taxes and insurance are reviewed — not to see if you can afford a payment (there isn't one) but to confirm you can keep up with the obligations that keep the loan in good standing.
An FHA appraiser values the home. Proceeds are based on the youngest borrower's age, the appraised value (up to program limits), and current interest rates.
Fairway's dedicated reverse underwriting team reviews the file. You sign, and on a refinance you have a three-business-day right to change your mind before any money moves.
Keep paying taxes, insurance and HOA dues, keep the home up, and live there. Each year you confirm occupancy. That is the ongoing job — Scott stays a text away for the rest.
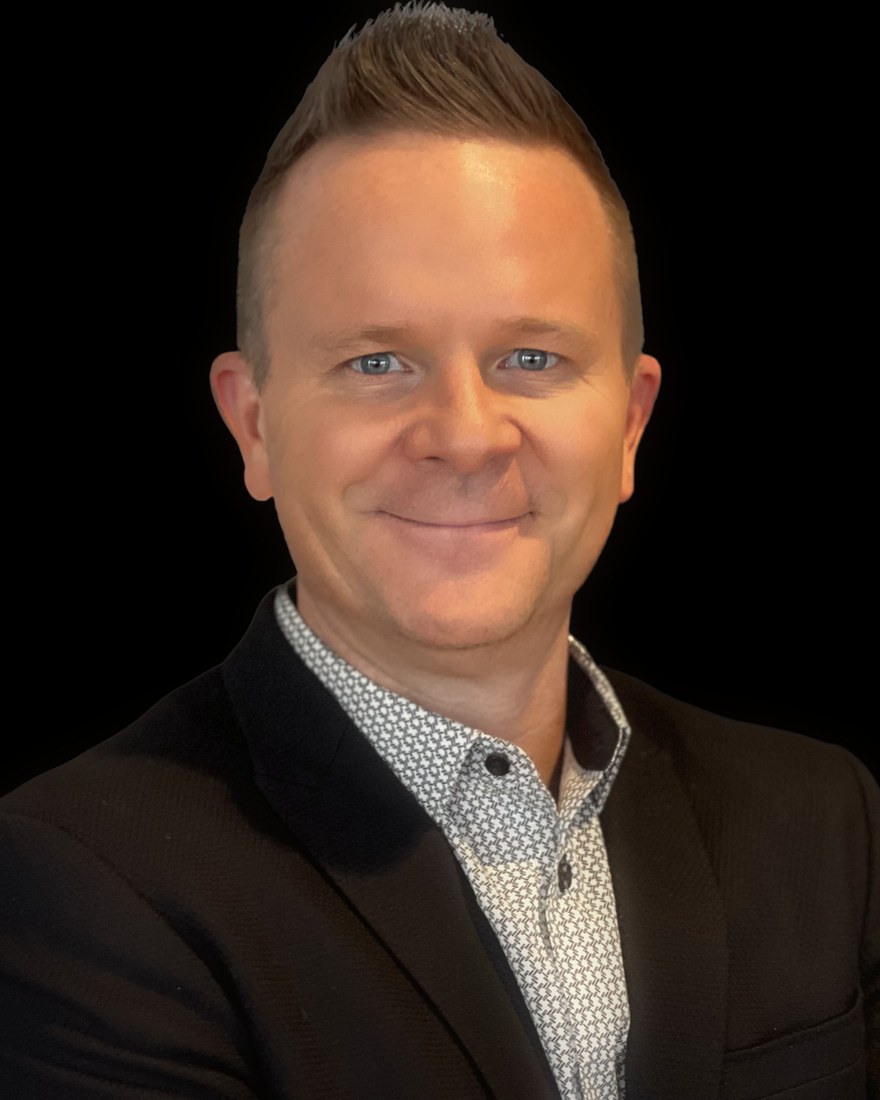
Your point of contact
Most reverse mortgage conversations happen with a specialist who only sells reverse mortgages. Scott Synovic has been in mortgage lending since 2003, originates conventional, FHA, VA, USDA and jumbo loans every week — and originates reverse mortgages through Fairway Reverse, Fairway's dedicated reverse division with its own underwriting, processing and support teams.
So when he says a reverse mortgage fits, it is because it beat the refinance, the HELOC and doing nothing on your numbers — not because it was the only thing on the shelf. And when it does not fit, you will hear that first.
Three ways to turn home equity into money, compared honestly by someone who originates all three.
5 min read →Scott · Loan OfficerStraight answers
A reverse mortgage is a loan for homeowners 62 and older that converts part of the equity in a home into cash — as a lump sum, a line of credit, monthly payments, or a combination — with no required monthly mortgage payment. The most common type is the Home Equity Conversion Mortgage (HECM), which is insured by the Federal Housing Administration. The borrower keeps the title, must continue to pay property taxes, insurance and HOA dues and maintain the home, and the loan is repaid when the last borrower sells, moves out permanently or passes away.
For a HECM: at least one borrower must be 62 or older, the home must be the borrower's primary residence, there must be enough equity (an existing mortgage is paid off with the proceeds), the property must be an eligible type, and the borrower must pass a financial assessment showing they can keep up with taxes, insurance and maintenance. HUD-approved counseling is required before applying. Scott Synovic originates reverse mortgages through Fairway Reverse for homeowners across Colorado.
Yes. Title stays in your name. The lender holds a lien, as with any mortgage. You can sell the home at any time and keep any equity above the loan balance.
When the last borrower passes away or leaves the home, the loan becomes due. Heirs can keep the home by paying the balance or 95% of the current appraised value (whichever is less), sell it and keep any remaining equity, or let the lender take the home. Because HECMs are non-recourse and FHA-insured, heirs never owe more than the home is worth when it is sold to repay the loan.
Property taxes, homeowners insurance, any HOA or condo dues, and upkeep of the home. You must also live in the home as your primary residence. Falling behind on these obligations can make the loan due and payable. There is no required monthly principal-and-interest payment, although you may make payments voluntarily.
Reverse mortgage proceeds are loan advances, not income, so they are generally not taxable — but this is not tax advice. Consult a tax advisor, and talk with a financial advisor about any effect on needs-based benefits such as Medicaid or SSI; Social Security and Medicare are not affected.
Yes. HECM for Purchase (H4P) lets buyers 62 and older purchase a primary residence with a larger down payment (typically a sizable percentage of the price, which depends on age and rates) and no required monthly mortgage payment afterward. It is common for downsizing, moving closer to family, or buying a single-level home.
It depends on the age of the youngest borrower, the home's appraised value (up to the HECM lending limit), and current interest rates — older borrowers and lower rates generally mean more available. Any existing mortgage is paid off first. Scott runs the actual numbers for your home at no cost and no obligation.
Yes. Every HECM applicant must complete a session with an independent, HUD-approved housing counselor before the lender can process the application. It typically takes about an hour and can be done by phone. It is one of the strongest consumer protections in the mortgage world, and Scott recommends it even to people who end up deciding against a reverse mortgage.
Scott Synovic is a Fairway Home Mortgage loan officer in Monument, CO (NMLS #253799) who originates both traditional and reverse mortgages and is listed on fairwayreverse.com, Fairway's dedicated reverse mortgage division. That means you get a comparison across every option — a reverse mortgage, a forward refinance, a HELOC, or waiting — from one person, with no pressure toward any of them.
Reverse mortgage disclosures: A reverse mortgage is a loan that must be repaid. Borrowers must be 62 or older (for a Home Equity Conversion Mortgage, or HECM), live in the home as their primary residence, and continue to pay property taxes, homeowners insurance, and any HOA dues, and maintain the home; failing to meet these obligations can result in the loan becoming due and payable and may lead to foreclosure. Interest and fees are added to the loan balance each month, so the balance grows over time and home equity decreases. The loan becomes due when the last borrower (or eligible non-borrowing spouse) no longer lives in the home as a primary residence, sells the home, or passes away. HECM loans are insured by the Federal Housing Administration (FHA) and are non-recourse: neither the borrower nor the heirs will owe more than the home is worth when the loan is repaid, as long as the home is sold to repay the loan. Borrowers must complete counseling with a HUD-approved independent counselor before applying. Proceeds are generally not considered taxable income, but this is not tax advice; consult a tax advisor, and consult a financial advisor about any effect on needs-based benefits such as Medicaid or SSI. This material is not from HUD or FHA and has not been approved by HUD or any government agency. Not all borrowers will qualify; proceeds depend on the age of the youngest borrower, the home's value, current interest rates and program limits.
Fairway Independent Mortgage Corporation is not affiliated with any government agency. These materials are not from, and were not approved by, HUD, FHA, VA, USDA, the Colorado Housing and Finance Authority (CHFA) or any other government agency. Educational content only; not financial, tax or legal advice. This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply.
Ready when you are
A question, a parent's situation, a mailer you want decoded — text it over. If a reverse mortgage is the wrong tool, you will hear that first, and you will still get the right one explained.
scott.synovic@fairwaymc.com · Fairway Home Mortgage — Monument, CO, 1832 Woodmoor Drive, Suite 106, Monument, CO 80132. Applications happen on Fairway's secure site — never here.
Back to the forward side
Done exploring reverse? Flip the whole site back over to buying, refinancing, first-time buyer guides and the payment calculator.
Flip to Forward