Scott Synovic, Loan Officer, NMLS #253799. Licensed in Colorado (100019385). Branch: 1832 Woodmoor Drive, Suite 106, Monument, CO 80132.
This is not an offer to enter into an agreement. Not all customers will qualify. Information, rates and programs are subject to change without notice. All products are subject to credit and property approval. Other restrictions and limitations may apply. Equal Housing Opportunity.
Fairway Independent Mortgage Corporation is not affiliated with any government agency. These materials are not from, and were not approved by, HUD, FHA, VA, USDA, the Colorado Housing and Finance Authority (CHFA) or any other government agency.
Scott Synovic and Fairway Independent Mortgage Corporation are not real estate brokerages. Buyers may work with any licensed real estate agent of their choosing, and no real estate professional is required to use any particular lender.
This website is educational and collects no personal information: no forms, no analytics, no tracking pixels, no cookies set by this site. Applications and document uploads happen inside Fairway's secure systems, never on this website.
Reverse mortgage disclosures: A reverse mortgage is a loan that must be repaid. Borrowers must be 62 or older (for a Home Equity Conversion Mortgage, or HECM), live in the home as their primary residence, and continue to pay property taxes, homeowners insurance, and any HOA dues, and maintain the home; failing to meet these obligations can result in the loan becoming due and payable and may lead to foreclosure. Interest and fees are added to the loan balance each month, so the balance grows over time and home equity decreases. The loan becomes due when the last borrower (or eligible non-borrowing spouse) no longer lives in the home as a primary residence, sells the home, or passes away. HECM loans are insured by the Federal Housing Administration (FHA) and are non-recourse: neither the borrower nor the heirs will owe more than the home is worth when the loan is repaid, as long as the home is sold to repay the loan. Borrowers must complete counseling with a HUD-approved independent counselor before applying. Proceeds are generally not considered taxable income, but this is not tax advice; consult a tax advisor, and consult a financial advisor about any effect on needs-based benefits such as Medicaid or SSI. This material is not from HUD or FHA and has not been approved by HUD or any government agency. Not all borrowers will qualify; proceeds depend on the age of the youngest borrower, the home's value, current interest rates and program limits.
Copyright © 2026 Fairway Independent Mortgage Corporation. NMLS #2289 (NMLS Consumer Access). 4750 S. Biltmore Lane, Madison, WI 53718, 1-866-912-4800. Fairway Home Mortgage is a dba of Fairway Independent Mortgage Corporation. All rights reserved. Licenses & disclosures · Site disclosures
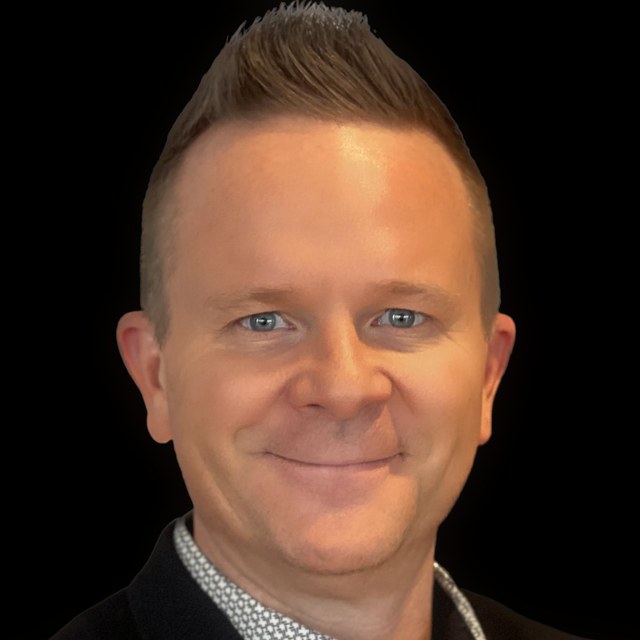
 Scott · Loan Officer